 US Market
Stock Activity:
ALL USD Stocks

Chat Now !

Lowe’s Punished by Investors for Not Growing Like Home Depot
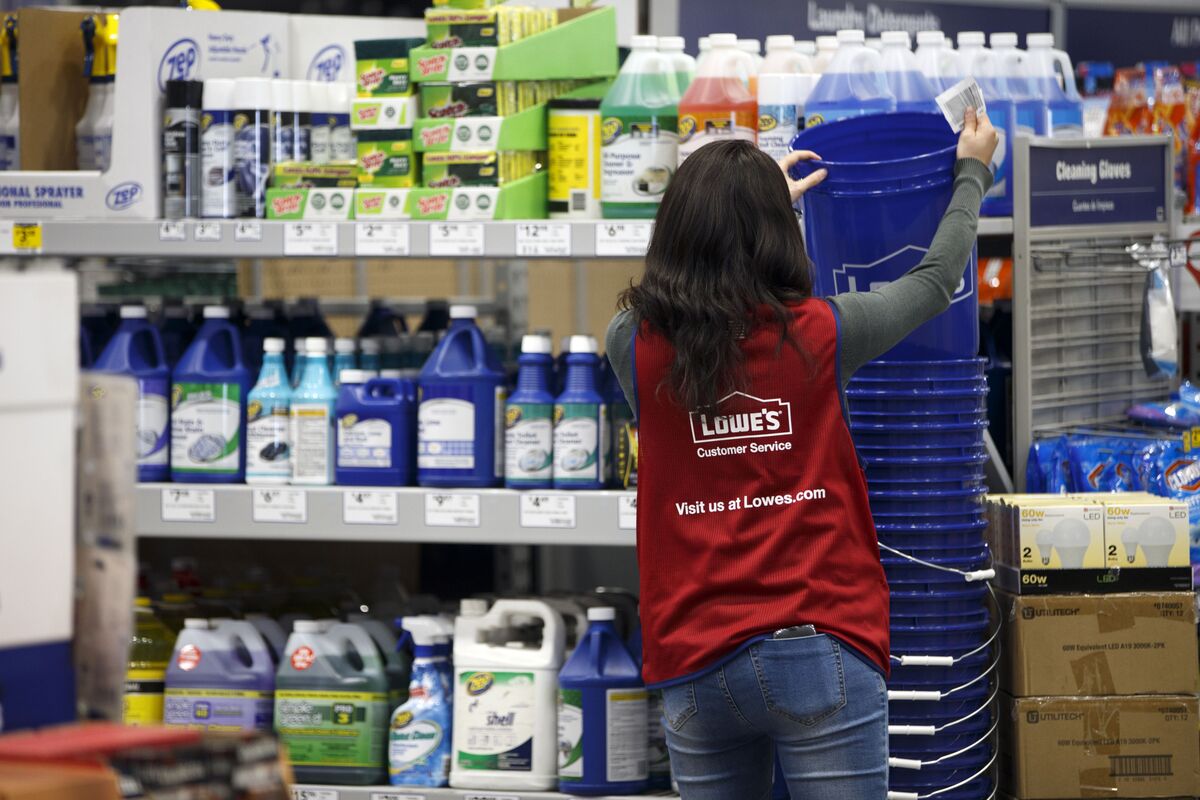
The continued boom in U.S. housing prices seems to favor Home Depot Inc. over rival Lowe’s Cos.
The continued boom in U.S. housing prices seems to favor Home Depot Inc. over rival Lowe’s Cos.
Lowe’s, the second-largest U.S. home-improvement chain, reported fourth-quarter earnings that missed analysts’ estimates, sending the shares down as much as 6 percent in premarket trading.
After almost a decade of rising property values, Americans are increasingly seeing their homes as investments, and renovating them at a record pace. Home-improvement chains have benefited, with sales growth outpacing much of the retail industry. But Lowe’s isn’t getting as much of a lift as its larger competitor.
Lowe’s shares fell as low as $89.69 in premarket trading. They had gained 25 percent in the past year.
Excluding some items, profit amounted to 74 cents a share, the company said in a statement. Analysts on average projected 87 cents.
The key metric of same-store sales rose 4.1 percent, topping analysts’ 3 percent estimate, according to Consensus Metrix. Home Depot posted a gain of 7.5 percent, marking the seventh-straight quarter it has outperformed Lowe’s.
Lowe’s provided its first forecast for this fiscal year, saying earnings per share will be $5.40 to $5.50 a share. Analysts predicted $6.01 a share, on average.
Even though millennials are starting families and buying more homes, there are signs that the housing market might be cooling off. Mortgage rates are rising amid inflation fears, with the 30-year rate climbing to 4.38 percent earlier this month, the highest since April 2014.
The company also benefited last quarter from spending to repair structures damaged during hurricane season.
Like many large companies after the federal tax overhaul went into effect, Lowe’s announced a one-time bonus of $1,000 for its hourly employees. It also expanded parental leave, to help retain workers in a tight labor market.